0-0-7
0-0-7
At ocean eleven
And now rudeboys have a go wail
'Cause them out of jail
Rudeboys cannot fail ...
Dem a loot, dem a shoot, dem a wail
A Shanty Town
Dem a loot, dem a shoot, dem a wail
A Shanty Town ...
I guess, we'll be adding into the Political Playbook is that you don't prosecute Wall Street mobsters, especially if they hail from Goldman Sucks , in an election year.
No Criminal Case Is Likely in Loss at MF Global
After 10 months of stitching together evidence on the firm’s demise, criminal investigators are concluding that chaos and porous risk controls at the firm, rather than fraud, allowed the money to disappear, according to people involved in the case ...
[snip]
In the most telling indication yet that the MF Global investigation is winding down, federal authorities are seeking to interview the former chief of the firm, Jon S. Corzine, next month, according to the people involved in the case. Authorities hope that Mr. Corzine, who is expected to accept the invitation, will shed light on the actions of other employees at MF Global.
Those developments indicate that federal prosecutors do not expect to file criminal charges against the former New Jersey governor. Mr. Corzine has not yet received assurances that he is free from scrutiny, but two rounds of interviews with former employees and a review of thousands of documents have left prosecutors without a case against him, say the people involved in the investigation who spoke on the condition of anonymity
And, it gets worse!
I mean, even this wouldn't be served in the Irony Cafe;
Mr. Corzine, in a bid to rebuild his image and engage his passion for trading, is weighing whether to start a hedge fund, according to people with knowledge of his plans. He is currently trading with his family’s wealth.
A New Mexico town once changed their name to "Truth or Consequences" ", to gain fame.
If a show came along named "No Consequences", Wall Street, and only Wall Street, with its' larcenous infamy, would have to lay claim to it.
File this one under "Laughing all the way - running away from the bank" ...
Help Me Mr. Wizard! 
Bonus Links
Another Week, Another Bankster with Impunity
What a World - There Is No "Manslaughter" Charge in Financial Firm Incompetence
Jon Corzine Wants to Start a Hedge Fund, Maybe
Thursday, August 16, 2012
Corzine Passes Go, Collects $200


Monday, November 21, 2011
Everyday People ... Stand!
Sly and the Family Stone - Everyday People
Totally Outrageous!
Police pepper spraying and arresting students at UC Davis
And sorry, to those Police State Mouthpieces, who are endorsing this, saying it would prevent worse injuries.
I call BULLSHIT!
Look at the above, now look, when the shoe is on the other foot.
UC Davis Chancellor Katehi walks to her car (higher quality)
To you, Officer Pike (the cretin pepper sprayer) and to you Chancellor Linda Katehi, the world IS watching!
So is Will Bunch, over on Attytood
This much is clear: The campus cops 3,000 miles away have offer a blueprint of what not to do. The swelling tide of police violence against peaceful demonstrators comes after 10 years of citizens’ passive acquiescence toward the Patriot Act and expanded government snooping, waterboarding terror suspects, and giving urban police departments more high-tech firepower than many Third World nations. Now our security-state-on-steroids is being turned against non-violent protesters here in the “homeland.” Talk about blowback!
Take us out, Sly ...
Sly and the Family Stone - Stand!
Thursday, November 03, 2011
Top Ten Cloves: Possible New Fees Banks Will Start Charging
News Item: Banks likely to try range of new fees
10. The Kardashian Charge - Get divorced after 72-days, fees, fees, fees ...
9. Don't have your own Deposit or Withdrawal Slips? ... Just rent one of the banks, for a fee
8. ATM's will have "Coin Slots" (like old public pay phones) if you want to use them
7. HuffPo Model: You can work at the bank, not get paid salary - and get charged with a fee
6. Need to speak to the Bank Manager? ... You can book time with him, for a fee ...
5. Fee for just walking into the bank
4. Don't have a pen to write out deposit/withdrawal slip? ... Bank has one, for a fee ...
3. The Jeopardy Fee; You didn't phrase your transaction request in the form of a question
2. Car loans, instead of based on amount/time/years/, will be based on cars' weight
1. Groucho Marx Fee - Don't know the Secret Word, it will cost you a $100 fee

(Image courtesy of Tom Priest at "In a Nutshell")
Bonus Riffs
Will Oremus: Fee-Market Capitalism - Bank of America learns it has to be more subtle about screwing its customers.
Lauri Apple: More Banks Scrap Debit Card Fee Idea
Even The S.E.C Thinks Goldman Sucks!
Wednesday, March 31, 2010
How's Goldman Sachs Going To Exploit This?
Certain individuals, particularly centered on those with a gambling problem, have been known to "bet the house", from time-to-time.
Now, thanks to some new "innovative financing", they can also "bet the stadium" (perhaps, along with the house).
Colleges offering ‘sports mortgages’Now, combine that frustration with cash-strapped college athletics departments, struggling to upgrade aging stadiums, and you’ve got the latest innovation in marketing for big-time athletics — the sports mortgage.
At Kansas, Jayhawk fans who sign up to pay up to $105,000 over 10 years will earn the right to buy guaranteed top seats for football over the next three decades. In return, the seats themselves will stay locked in at 2010 prices.
[snip]
The new pricing plans are known as “equity seat rights,’’ and are being pitched as a win-win for fans and teams. Diehard fans can be certain of what they’ll pay to see their favorite team well into the future — and can always sell tickets in the secondary market while taking a tax write-off for donating to a school. Teams can bank on extra revenue and avoid borrowing.
Stadium Capital Financing Group, the Chicago company behind the change, says it has the potential to transform how both college and pro teams court their most loyal fans. They’re confident sports mortgages will overtake the personal seat license, which doesn’t necessarily lock in ticket prices.
Okay, we're coloring outside the lines here, putting the ol' thinkin' caps on.
But what happens if the mortgage company, perhaps due to other investments, tanks?
How's Goldman Sachs going to exploit this?
Does, say, Goldman Sachs raise there hand, purchase the company, chop up the companies debt, and start selling "Stadium Derivatives", essentially just repackaging their programs that helped tank the world's economy?
Sports Mortgages?
Sounds like "three-yards-and-a-cloud-of-a-financial-mess" getting ready to come out of the locker room.
Bonus Goldman Sucks Riffs
Matt Taibbi: The Great American Bubble Machine
Paul Krugman: The Joy of Sachs
John Cook: Congrats Goldman Sachs! You're the New Symbol of Banker Greed
Survey Shows Name Should Be "Goldman Sucks"
Yet More Reasons The Survey Says Goldman Sucks!
Today's Ignorant Dolt - Brian Griffiths, of Goldman Sachs
Sunday, March 21, 2010
The Next PartyofNoican War
Good Frank Rich today, as he lays out the next front for Mitch McConnell and John Boehner to lie, distort, and, otherwise, continue their gameplan of obstructionism.
Obama, Lehman and ‘The Dragon Tattoo’Anger over the last crash and the bailout of its high rollers spans the political spectrum, from neo-New Dealers on the left to Tea Party protesters on the right. As the battle over financial regulatory reform began in earnest with Chris Dodd’s introduction of a Senate bill last week, Lewis told an interviewer, “There is a war that is about to happen over not just who regulates Wall Street but what the rules are.”
The question for the politicians at the center of this battleground is simple enough: Which side of the war are they on? The Republican leadership revealed its hand unequivocally last week. Addressing the American Bankers Association, the party’s House leader, John Boehner, promised to delay and fight any finance-reform bill. “Don’t let those little punk staffers take advantage of you, and stand up for yourselves,” Boehner instructed the poor, defenseless bankers. In late January he met the chief executive of JPMorgan Chase, Jamie Dimon, to make a pitch for donations. That may have been unnecessary. Chase and its employees, an A.T.M. for the Democrats in 2008, gave 73 percent of their contributions to the G.O.P. in the fourth quarter of 2009.
Republicans in the Senate will be no different. Mitch McConnell’s strategy of unmitigated obstructionism remains gospel there. Just as Charles Grassley and Olympia Snowe played the Democrats with months of fruitless negotiations on health care reform, so Richard Shelby and Bob Corker have been stalling a financial reform bill with similarly arid feints at “bipartisanship.” Corker insisted that any bill exclude regulation of extortionate “payday lenders,” who just happen to be among his biggest campaign contributors.
No doubt they will still be whining about healthcare, as they rev up the Right Wing Freak Show to go out and defend, honor and shower with platitudes, the slimeball Wall Street dwarfs, finks, phonies and frauds, who pulled the greatest heist in our history, thanks, in large part, to all that PartyofNoican deregulation.
Well, it will pump up the economy, to the extent Cable News covers it, and how many empty talking heads they rope in, and the shields we'll have to purchase, from all the flying bullshit that comes with it.
Monday, January 25, 2010
Breaking! ... Super Bowl In Doubt, As Obama Considers Bailout For Jets
Sources tell The Garlic that, in his State-on-the-Union address Wednesday evening, President Barack Obama will lay out steps to a program that will delay the Super Bowl, scheduled for February 7th, so that a bailout plan for the New York Jets can be worked out.
Obama will cite that the "hopes and dreams" of New York Jets fans are "too big to fail", and that it is imperative for the government to step in, a prevent a complete meltdown.
The Jets lost yesterday, to the Indianapolis Colts, in the AFC Championship game, giving them the berth in the Super Bowl, against the New Orleans Saints, who beat the Minnesota Vikings, in the NFC Championship game.
Additionally, unnamed Administration officials were looking for a "Katrina-Sept 11th Super Bowl", to augment other metaphorical imagery the President will have in his SOTU speech;"We need to build a bridge, from Namath, to New Orleans, so that the engine of passion, held so dearly by Jets and Saints fans, two cities badly scarred in our recent history, can continue to rumble, to resonate, and be a beacon to our continued economic growth.
Details of the Jets Bailout plan are sketchy, and it is not clear if it will contain oversight, or regulations, limiting bonuses of team executives.
A spokesperson for the NFL indicated the league is in discussions with the Obama White House, and, should the Super Bowl be delayed, the plans would be to continue with celebrity-filled parties, and television programs highlighting Super Bowl commercials.
Thursday, January 07, 2010
Restart Those "Geithner Goes" Office Pools
Whoever, in the first round, got a date in 2010, for when Secretary of the Treasury Timothy Geithner takes a hike, forced or otherwise, may be looking a bit more optimistic today;
Geithner’s New York Fed Told AIG to Limit Swaps Disclosure Share Business ExchangeThe Federal Reserve Bank of New York, then led by Timothy Geithner, told American International Group Inc. to withhold details from the public about the bailed-out insurer’s payments to banks during the depths of the financial crisis, e-mails between the company and its regulator show.
AIG said in a draft of a regulatory filing that the insurer paid banks, which included Goldman Sachs Group Inc. and Societe Generale SA, 100 cents on the dollar for credit-default swaps they bought from the firm. The New York Fed crossed out the reference, according to the e-mails, and AIG excluded the language when the filing was made public on Dec. 24, 2008. The e-mails were obtained by Representative Darrell Issa, ranking member of the House Oversight and Government Reform Committee.
The New York Fed took over negotiations between AIG and the banks in November 2008 as losses on the swaps, which were contracts tied to subprime home loans, threatened to swamp the insurer weeks after its taxpayer-funded rescue. The regulator decided that Goldman Sachs and more than a dozen banks would be fully repaid for $62.1 billion of the swaps, prompting lawmakers to call the AIG rescue a “backdoor bailout” of financial firms.
“It appears that the New York Fed deliberately pressured AIG to restrict and delay the disclosure of important information,” said Issa, a California Republican. Taxpayers “deserve full and complete disclosure under our nation’s securities laws, not the withholding of politically inconvenient information.”
Oh, Timmy, you didn't do that ...
Oh, Timmy, Timmy, Timmy ...
There's little refuge out there, Timmy.
Henry Blodget; Bloomberg unearths more details on the nauseating bailout of AIG and the 100-cents-on-the-dollar payouts to Goldman, et al.
Once again, Tim Geithner was in charge.
Barry Ritholtz;Between Summers and Geithner, it appears that President Obama has made the exact same mistake that one George W. Bush did: Instead of filling his administration’s most important posts with his own people, he reached back to prior admins (Cheney, Rumsfeld, etc) and loaded up on incompetent retreads.
Barack W. Obama indeed . . .
Felix Salmon points out another fact that Timmy, probably, would like to bury;Michael Corkery also points out that all of this secrecy coincided with Geithner’s nomination to be Treasury secretary, which makes the whole thing stink much more: was Geithner deliberately trying to keep anything potentially damaging secret for the sake of his own personal career progression?
And, Edward Harrison, writing on Naked Capitalism, just lets it all out;Let me add a few words to Yves’ last post because I don’t think she was explicit enough about what’s going on here. This was looting and a cover-up plain and simple.
[snip]
He was on the job when these firms levered up and took reckless risks that endangered our financial system. For him to absolve himself of responsibility is a disgrace. And to add insult to injury, we now learn that he urged a systemically important company to withhold evidence of his looting of taxpayers.
Tim Geithner must go
Now, we wait, to see what Congress does, and if they will go after Geithner, and, for that matter, Heistin' Hank Paulson, for their total scam rip-off of the Treasury, the citizens, the country.
And, for those holding squares, say, in Spring (the Obama White House will want to get this off the radar well before the Fall Midterms), you're sitting pretty ...
Bonus Riffs
Susie Madrak: Geithner to AIG: Let's Keep This Under Our Hat, Okay?
Cynthia Kouril: Geithner’s New York Fed Ordered AIG to Violate Securities Law in 2008
Breaking! ... Obama Takes Action, Siezes AIG's March Madness Office Pools and Brackets
Blame?
This Didn't Make The 11PM News ...
Greed Has A Name ...
Friday, August 21, 2009
And, In The "Fuck You Very Much" Department ...
If Digby had her way, she would call it, simply, hubris.
New Chief at A.I.G. to Be Paid at Least $7 Million a YearHow much will it cost the American International Group to keep its chief executive to help stabilize the troubled insurer? At least $7 million a year.
Oh, "clawbacks" ... That may be too harsh, right?
A.I.G. disclosed Monday in a regulatory filing that it would pay Robert H. Benmosche, 65, the former head of MetLife, $3 million a year in cash and $4 million in stock.
Mr. Benmosche will also be eligible for up to $3.5 million in stock as part of an incentive plan, A.I.G. said in a regulatory filing.
[snip]
A.I.G. said in its letter formally offering Mr. Benmosche the job that his compensation would be subject to “clawbacks” by Mr. Feinberg’s office, meaning that at least some of the money could be recovered if the bonuses were paid based on financially misleading data. Mr. Benmosche will also not receive a severance package if he is dismissed from the company, according to the regulatory filing.
I mean, AIG, and "financially misleading data ...
I'm sure we have absolute no worries there ...
And, there is this gem;This month, A.I.G. reported its first quarterly profit since 2007, though Mr. Liddy warned that the insurance businesses “remain challenged.”
Really?
AIG has paid back all the money, the billions-upon-billions, given to them by the U.S. Government, and still made a profit?
How come that wasn't in screaming headlines?
Yeah, the insurance business may remained "challenged", but with the Obama Financial Team (Ruben and, of course Secretary of the Treasury Tim "What's that, Lassie? (Woof, woof!!) Timmy Geithner's in the well?!!" Geithner), at the helm, there's no worry.
A bailout, simply, is just around the corner.
And, when we want to look into the "Clueless Corner", Yves Smith, over on Naked Capitalism, had this;Tim Duy pointed out this priceless remark from AIG's new CEO, Robert Benmosch:
This ought to be rather interesting to watch.
Benmosche told employees that he “had the luxury to say to the government, I’m not going to rush to do this. I’m appalled at how much pressure has been put on all of you to just sell it no matter what, because the Fed wants out, or the Treasury wants out. If they want out in a hurry, they shouldn’t have come in in the first place.”
That is, how soon into the "Benmosch Dynasty", does AIG come whimpering to Washington again, begging for money.
Bonus AIG Riffs
Dennis Overbye: They Tried to Outsmart Wall Street
Larisa Alexandrovna: AIG = BCCI
Eliot Spitzer: The Real AIG Scandal - It's not the bonuses. It's that AIG's counterparties are getting paid back in full
Paul Krugman: AIG
Michael Lewis: The Man Who Crashed the World
Zachary Roth and Ben Buchwalter: The Rise And Fall Of AIG's Financial Products Unit
Breaking! ... Obama Takes Action, Siezes AIG's March Madness Office Pools and Brackets
Monday, August 10, 2009
Shorter Krugman: Yeah Big Government!
We have to defer to D-Day, for "Headline of the Day";
Paul Krugman: making heads explode everywhereSo I recommend you read Paul Krugman, like usual. This piece will make right-wing heads explode even more than anything else I've cited from him. Especially this part:
No doubt, Reagan's #1 Groupie, Peggy Noonan, has already made the call, for the delivery of a case of wine, and is refilling her prescription meds, so she can hunker down and defend her beloved hero.
All in all, then, the government has played a crucial stabilizing role in this economic crisis. Ronald Reagan was wrong: sometimes the private sector is the problem, and government is the solution.
As usual, Paul Krugman has been keeping his eye of the ball, and presents measured optimism that things are, slowly, very slowly, heading towards the better;
Averting the WorstFor all that, however, the latest flurry of economic reports suggests that the economy has backed up several paces from the edge of the abyss.
That's right, the PartyofNoicans arch enemy, Big Government, is running in to save the day.
A few months ago the possibility of falling into the abyss seemed all too real. The financial panic of late 2008 was as severe, in some ways, as the banking panic of the early 1930s, and for a while key economic indicators — world trade, world industrial production, even stock prices — were falling as fast as or faster than they did in 1929-30.
But in the 1930s the trend lines just kept heading down. This time, the plunge appears to be ending after just one terrible year.
So what saved us from a full replay of the Great Depression? The answer, almost surely, lies in the very different role played by government.We don’t know what the economic policies of a McCain-Palin administration would have been. We do know, however, what Republicans in opposition have been saying — and it boils down to demanding that the government stop standing in the way of a possible depression.
Something Robert Stein agrees with;
I’m not just talking about opposition to the stimulus. Leading Republicans want to do away with automatic stabilizers, too. Back in March, John Boehner, the House minority leader, declared that since families were suffering, "it’s time for government to tighten their belts and show the American people that we ‘get’ it." Fortunately, his advice was ignored.It will take months, even years, before the verdict is in on the wisdom of every aspect of the enormous Obama spending and deficit growth, but one thing is already clear: All that furious activity has been more reassuring than a President McCain approach of tax cuts and hoping for the best.
If you happen to work with, or live near, any Right Wing Freak Show Flying Monkeys, you may want to bring along your rain slicker.
Krugman promoting Big Government should get them flinging their feces around.
The Queen Monkey, Michelle "Staklin" Malkin, has already issued the clarion call.
Saturday, August 08, 2009
Survey Shows Name Should Be "Goldman Sucks"
This had to be, perhaps, the most "Duh!" happening of the week;
Goldman Sachs’ reputation tarnishedGoldman Sachs’ reputation among both the general public and financially sophisticated Americans has been damaged by the events of the past year, according to research conducted for the Financial Times.
In a survey of 17,000 Americans, Brand Asset Consulting found that Goldman’s stature – as measured by several gauges of brand strength – had suffered in 2008 and 2009.
“Goldman Sachs still has that Gordon Gekko look to it among the general public,” said Anne Rivers, who oversaw the survey, referring to the villain of the 1987 film Wall Street.
[snip]
In Rolling Stone last month, Goldman was described as a “great vampire squid wrapped around the face of humanity”. The headline on the cover of New York magazine last week asked: “Is Goldman Sachs evil? Or just too good?” The subsequent article argued in favour of the former, with a tip of the cap to the latter
[snip]
However, some marketing professionals say the storm will pass. “All of this giant squid language they can pretty much brush off,” said William Barker of Brand Finance. “My guess is that their customers are probably very happy with them.”
In July, Goldman reported record quarterly profits of $3.44bn on revenues of $13.8bn.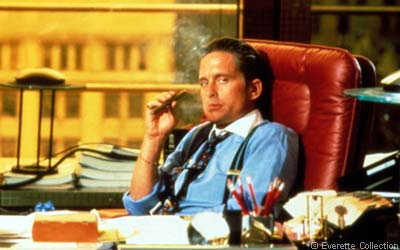
Yeah, thanks to all the bailout, and other government, money.
Then again, Goldman Sucks isn't playing to (or with) the peanut gallery.
From Joe Weisenthal;But then, who cares what the general public thinks? Do the Goldman traders care? Nope. Do college graduates, knowing that Goldman is the home of TARP-free high pay care? Nope. Goldman isn't selling 401(k)s or $7 stock trades to the retail investor. What matters is how Goldman is perceived by the professional classes, and to some extent they've always been hated by those on the outside. Big deal.
I suppose, it is conceivably, that in the not-so-distant future, along with all the tax, unemployment, 401K deductions listed on your pay stub, there'll be one for "Goldman Sucks" on it.
Meanwhile, Goldman shares look set to open around $165 today, over 300% off their lows from the crisis. If this reputational hit mattered, nobody bothered to tell paid-up Goldman Sachs shareholders.
Bonus Goldman Sucks Riffs
John Cook: Congrats Goldman Sachs! You're the New Symbol of Banker Greed
Paul Krugman: The Joy of Sachs
dday: Goldman's Record Taxpayer-Subsidized Profits
Nick Baumann: Even the Wall Street Journal Hates Goldman Now
Matt Taibbi: The real price of Goldman’s giganto-profits
Tuesday, April 28, 2009
Shorter Krugman - Smack! ...Upside The Head!
"In 2008, overpaid bankers taking big risks with other people’s money brought the world economy to its knees. The last thing we need is to give them a chance to do it all over again."
We meant to get this up yesterday, but some kind of Flu-thing knocked this out of the box.
It seems, that, happy-days-are-here-again, if you read the article in the Saturday New York Times;
After Off Year, Wall Street Pay Is Bouncing BackWorkers at the largest financial institutions are on track to earn as much money this year as they did before the financial crisis began, because of the strong start of the year for bank profits.
[Snip]
If that pace continues all year, the money set aside for compensation suggests that workers at many banks will see their pay — much of it in bonuses — recover from the lows of last year.
Hmmmm ... Then why do we keep hearing that Wall Street is going to need billions more to stay afloat?
Well, on Sunday, Nobel Prize Winner Paul Krugman was having none of that.
Money for NothingRemember that the gilded Wall Street of 2007 was a fairly new phenomenon. From the 1930s until around 1980 banking was a staid, rather boring business that paid no better, on average, than other industries, yet kept the economy’s wheels turning.
Those fat cats on Wall Street are going to need some of that extra dough - for make-up, to cover up the palm print of Krugman's slap, upside-the-head.
So why did some bankers suddenly begin making vast fortunes? It was, we were told, a reward for their creativity — for financial innovation. At this point, however, it’s hard to think of any major recent financial innovations that actually aided society, as opposed to being new, improved ways to blow bubbles, evade regulations and implement de facto Ponzi schemes
[Snip]
Still, you might argue that we have a free-market economy, and it’s up to the private sector to decide how much its employees are worth. But this brings me to my second point: Wall Street is no longer, in any real sense, part of the private sector. It’s a ward of the state, every bit as dependent on government aid as recipients of Temporary Assistance for Needy Families, a k a “welfare.”
I’m not just talking about the $600 billion or so already committed under the TARP. There are also the huge credit lines extended by the Federal Reserve; large-scale lending by Federal Home Loan Banks; the taxpayer-financed payoffs of A.I.G. contracts; the vast expansion of F.D.I.C. guarantees; and, more broadly, the implicit backing provided to every financial firm considered too big, or too strategic, to fail.
One can argue that it’s necessary to rescue Wall Street to protect the economy as a whole — and in fact I agree. But given all that taxpayer money on the line, financial firms should be acting like public utilities, not returning to the practices and paychecks of 2007.
Bonus Riffs
This Didn't Make The 11PM News ...
In A Nutshell ...
Breaking! ... Obama Takes Action, Seizes AIG's March Madness Office Pools and Brackets
A Night At The Wall Street Meltdown
Rich on Ruben: "The Citi may never sleep, but he snored ..."
Top Ten Cloves: Things About Citigroup Keeping Stadium Sponsorship After Getting Government Bailout
Thursday, April 09, 2009
Like Bush, Obama Wants Us To Go Shopping
Hmmmm ...
On a day where someone in the Administration (or a friendly) leaks out that "Hey, surprise, the banks are acing those Stress Tests", comes another floater that, get this, we, the public, should buy stocks and bonds of those toxic assets that the banks don't want to keep (but want to get paid for, just the same).
U.S. Imagines the Bailout as an Investment ToolDuring World War I, Americans were exhorted to buy Liberty Bonds to help their soldiers on the front.
Now, it seems, they will be asked to come to the aid of their banks — with the added inducement of possibly making some money for themselves.
As part of its sweeping plan to purge banks of troublesome assets, the Obama administration is encouraging several large investment companies to create the financial-crisis equivalent of war bonds: bailout funds.
The idea is that these investments, akin to mutual funds that buy stocks and bonds, would give ordinary Americans a chance to profit from the bailouts that are being financed by their tax dollars. But there is another, deeply political motivation as well: to quiet accusations that all of these giant bailouts will benefit only Wall Street plutocrats.
WTF!
Is this the Summers and Geithner version of the Clean Skies Act?
And, right there is the rub.
All those billions in bailouts are benefiting only those "Wall Street plutocrats"
Christ, I mean, the whole game has been rigged for them.
Now, the Obama Team wants to go into to backwoods carny mode, telling us to "Step right here ...Have we got a deal for you"?
So, along with already giving the dwarfs, finks, phonies and frauds of Wall Street our tax dollars, we are supposed to slip on the Uncle Sam suit, go all-jingoistic and start giving them our "disposable income"?
Will there be retro-Dough Boy posters, substituting soldiers, with slimy "financial instrument" sellers, extorting us to "Get into the Fight - Buy Toxic Asset Bonds"?
The embrace of smaller investors underscores the concern in Washington and on Wall Street that Americans’ anger could imperil further efforts to stimulate the economy with vast amounts of government spending. Many Americans say they believe the bailout programs — and the potentially rich profits they could yield — will benefit only a golden few, including some of the institutions that helped push the economy to the brink.
No shit, Dick Tracy!For the investment managers, the benefits are potentially large. These big firms can charge healthy fees to investors for taking part. They will also have the marketing prestige of being the firms the government turns to at a time of crisis to help sort out the country’s financial mess.
Oh please, give me a break!
Translation here is "They will also have the marketing prestige of being the Governments' hand-picked front man"
We made reference to this once, already, but it looks more-and-more like the Obama Administration has hired the Lincoln Group to hawk their shit.
And those Bank Stress Tests ...
"Romper, bomper, stomper boo. Tell me, tell me, tell me, do. Magic mirror, tell me today. Have all banks had fun at play?"
From Yves Smith;The whole point of this charade exercise was to show the big banks weren't terminal but still needed dough, and I am sure it will prove to be lots of dough before we are done. But they now have the Good Housekeeping seal, so the chump taxpayer can breathe easy that the authorities are taking prudent measures to make sure his money is being shepherded wisely.
It’s been awhile, but this is a legitimate moment of crises;
If you believe that, I have a bridge I'd like to sell you.
[Snip]
How does one parse tripe like this? First, the public private partnership program, aka cash for trash, is voluntary. Banks are not being compelled to sell. The idea that the banks "have to sell" is a canard. Second, the gaming of the program has already started (notice no lecture from Geithner about that?), so there is pretty much no risk that anyone will take a loss on the values they have in their books. The best summation of how bad this will get is from Rortybomb, who expects all the old Enron tricks to be employed (notice the terms of the PPIP prohibit the fund managers from gaming the process, not the banks trading among themselves. You can drive a truck through this oversight. And the Treasury has remained silent as the banks themselves have been loading up their balance sheets with toxic sludge, paying more than private investors are willing to bid).
I'm sure all the bankers understand full well the massive disconnect between talk and action, and are dutifully following Treasury's lead in maintaining appearances.
Help Me Mr. Wizard!
Wednesday, April 08, 2009
Follow-Up To Screwing JP Morgan Chase (and others)
Well, things are moving along at a brisk pace.
Just last evening, highlighting the plight of Mr. and Mrs. Emptywheel, from Firedoglake, news is busting out all over today, on some protestin' and activism taking place soon.
From Jane Hamsher;
Want to Join Marcy and Me to Protest Banks on Saturday, April 11?On Saturday, April 11, there are going to be demonstrations all across America to protest what the banks are doing to the country.
There's a petition you can sign, and a Facebook Group you can join.
No, not the stupid teabagger protests, where people who never cared about George Bush spending like a drunken sailor are suddenly "fiscally responsible," and want to hold hands and blame black people for taking out subprime loans. We're joining with A New Way Forward to demand real structural change to our financial system
[Snip]
We'll be talking about our campaign with Progress Michigan to boycott JP Morgan for trying to break the labor contracts and keep all the money for themselves by driving Chrysler into bankruptcy, even though they themselves are only alive because of $25 billion in taxpayer dollars.
No prisoners!
Bonus Riffs
Libby Spencer: Break up the banksters - Update
dday: JP Morgan Chase Greedier Than The Actual J.P. Morgan
Tuesday, April 07, 2009
Hit'em Where It Hurts - Support The Chase Boycott!
I wish I had a Chase bank account, just so I could go in there today and close it, much in the same manner as Emptywheel, over on Firedoglake.
Save American Jobs: Close Your Chase AccountHere's how I explained to the Chase people why we were closing our accounts.
I’m closing my Chase accounts because JP Morgan Chase has placed its corporate interests above the jobs and health care of the people of my community, unlike other banks that continue to invest in rebuilding Michigan.
JP Morgan Chase insists on putting Chrysler into bankruptcy
On Saturday, the Wall Street Journal reported that JP Morgan is “resisting government pressure to swap” its Chrysler debt for equity in a restructured Chrysler. But if JP Morgan refuses this swap, then Chrysler will be forced into bankruptcy within a month.
According to the Wall Street Journal, JP Morgan prefers bankruptcy because, “billions of dollars of government debt and the UAW retiree health-care obligation [would] be wiped out before the secured lenders [JP Morgan and other big banks] lose anything.” In other words, JP Morgan wants to force Chrysler into bankruptcy so it would get repaid before all other creditors—including Chrysler retirees and US taxpayers.
JP Morgan Chase has already gotten billions from US taxpayers
Mr. and Mrs. Emptywheel, after withdrawing their stash from Chase, "put that money into a credit union that's supporting Michigan, not trying to bankrupt it."
Bob Fertik agrees: Excellent idea. But could we take this idea one step further? What if we all took our money out of Big Banks and moved it into a "Blue Bank"?
Maybe, JP Morgan Chase, if they do this callous, cowardly, self-centered, "Me First" action, can hire Joe Pesci to do some new ads for them, to explain it all;
Obviously we're a pretty large group: 70 million of us voted for Barack Obama. We may not be rich, but if we each deposited $1,000 that would be $70 billion.
If we wanted to start from scratch, we could start a new credit union (assuming we could qualify as an "Association") or a bank. But why jump through all the startup hoops? If we collected deposit pledges worth a decent amount ($10 million?), we could negotiate with existing smaller banks to find one "worthy" of our collective funds.
[Snip]
This idea has many precedents, both in the U.S. and abroad. Perhaps the most famous is Amalgamated Bank, founded in 1923 by the Amalgamated Clothing Workers of America, which is a commercial bank chartered in New York with nationwide service ...
"Always the dollars ... Always the fuckin' dollars. ..."
Bonus Wall Street Meltdown Riffs
This Didn't Make The 11PM News ...
Top Ten Cloves: Things About Citigroup Keeping Stadium Sponsorship After Getting Government Bailout
Rich on Ruben: "The Citi may never sleep, but he snored ..."
In A Nutshell ...
We're All In The Dance
Breaking! ... Obama Takes Action, Siezes AIG's March Madness Office Pools and Brackets
Wednesday, March 11, 2009
Blame?
We ain't got no Blame. We don't need no Blame! I don't have to show you any stinkin' blame!
There's a lot of banditos out there, taking no blame for all the Fred C. Dobbs they suckered, and one of the biggest, today, takes to the pages of the Murdoch Street Journal for his turn at turning his back on the economic meltdown, saying "Don't Blame Me!"
Mr. Andrea Mitchell, aka Alan Greenspan, the former Fed Chief, pleads "The Fed Didn't Cause the Housing Bubble" and, of course, toes the party line of warning againts too much regulation.If it is monetary policy that is at fault, then that can be corrected in the future, at least in principle. If, however, we are dealing with global forces beyond the control of domestic monetary policy makers, as I strongly suspect is the case, then we are facing a broader issue.
Global market competition and integration in goods, services and finance have brought unprecedented gains in material well being. But the growth path of highly competitive markets is cyclical. And on rare occasions it can break down, with consequences such as those we are currently experiencing. It is now very clear that the levels of complexity to which market practitioners at the height of their euphoria tried to push risk-management techniques and products were too much for even the most sophisticated market players to handle properly and prudently.
However, the appropriate policy response is not to bridle financial intermediation with heavy regulation. That would stifle important advances in finance that enhance standards of living. Remember, prior to the crisis, the U.S. economy exhibited an impressive degree of productivity advance. To achieve that with a modest level of combined domestic and borrowed foreign savings (our current account deficit) was a measure of our financial system's precrisis success. The solutions for the financial-market failures revealed by the crisis are higher capital requirements and a wider prosecution of fraud -- not increased micromanagement by government entities.
Sorry, there, Mr. Mitchell ... Thank you for playing our game, and there is some lovely parting gifts for you.
Frank James, on The Swamp;Greenspan may be right that the bubble had less to do with the fed-funds rate than the massive mountain of cash from Asia Americans were able to borrow.
James also quotes a 2004 USA Today article, with Mr. Andrea Mitchel saying "Overall, the household sector seems to be in good shape ..." And ""American consumers might benefit if lenders provided greater mortgage product alternatives to the traditional fixed-rate mortgage ..."
But history will probably judge him more harshly than he appears willing to judge himself. A famous line holds that Federal Reserve chairs are supposed to take the punch bowl away to keep the financial party from getting too irrationally exuberant.
Greenspan, however, appeared to be in a festive mood too. In 2004, he sang the praises of adjustable rate mortgages, many of which have contributed to the financial and economic woes currently roiling the nation.
That, being the Adjustable Rate Mortgage that Wall Street was ladling out like happy soup.
And the big Ownership Society your boss, The Commander Guy, was spinning.
I'm with John Cole, over on Balloon Juice;And for the record- I want so much regulation of the financial sector that if someone at Goldman Sachs wants to take a piss, he has to get a hall pass from Dennis Kucinich. They don’t like it, they can move to Iceland and see how they feel about bankers.

Tuesday, February 10, 2009
This Didn't Make The 11PM News ...
All you can do is read this and go "WOW!"
From Tyler Durden, over on Zero Hedge;
How The World Almost Came To An End At 2PM On September 18
"LiveLeak has caught a scary moment of previously undisclosed insight by Paul Kanjorski where he reveals some facts that have not been captured by the media previously. At 2 minutes and 20 seconds in the video below, Democratic Representative Kanjorski explains how the Federal Reserve told Congress members about a "tremendous draw-down of money market accounts in the United States, to the tune of $550 billion dollars." According to Kanjorski, this electronic transfer occurred over the period of an hour or two. And it gets worse. Kanjorski paraphrases the following disclosure by Bernanke and Paulson:"On Thursday (Sept 18), at 11am the Federal Reserve noticed a tremendous draw-down of money market accounts in the U.S., to the tune of $550 billion was being drawn out in the matter of an hour or two. The Treasury opened up its window to help and pumped a $105 billion in the system and quickly realized that they could not stem the tide. We were having an electronic run on the banks. They decided to close the operation, close down the money accounts and announce a guarantee of $250,000 per account so there wouldn't be further panic out there.
If they had not done that, their estimation is that by 2pm that afternoon, $5.5 trillion would have been drawn out of the money market system of the U.S., would have collapsed the entire economy of the U.S., and within 24 hours the world economy would have collapsed. It would have been the end of our economic system and our political system as we know it.
Hmmm ... Doesn't sound like Sam Wainwright, and a boat full of "Hee-Haws" would have helped here.
Who was pulling the money out?
Where did it go?
Someone gaming the system?
Yeah, I know, $550-Billion, that could have been just a few of the Wall Street CEO's pulling out their bonuses.
Actually, it had to do with the Lehman Brothers crash.
Olbermann had Daniel Gross of 'Newsweek' on to give the rundown of what went down.
The frightening part of it is ... Well ... There isn't anything preventing it from happening again.
Monday, December 08, 2008
Greed Has A Name ...
Boy, I think it's time he turns in his super secret "Industry Titan" decoder ring, the footed pajamas, with his name, and "Industry Titan" under it, on them, and, he gets kicked out of the treehouse.
Merrill Chief Wants $10-Million Bonus For Presiding Over $11-Billion LossMerrill Lynch chief John Thain wants a bonus of as much as $10 million, reports (sub. req.) the Wall Street Journal.
The Journal notes some evidence in Thain's favor:
Merrill's compensation committee is, not surprisingly, said to be objecting, pointing out among other things that, due to the dire economic situation, other firms like Goldman Sachs -- which did better than Merrill -- are forgoing bonuses this year.
Merrill has lost almost $12 billion this year, and is about to be taken over by Bank of America. Its shares have fallen from $50 when Thain took over late last year to $13.04 at close of trading Friday.
Mr. Thain's decision to sell Merrill likely salvaged billions of dollars for shareholders and saved a huge number of jobs at the firm, even though thousands of positions will be eliminated following the takeover.
Please ...
Mr. Thain's quick moves won him respect on Wall Street, especially in contrast to top executives at Lehman Brothers Holdings Inc. and Bear Stearns.
Isn't that like patting an arsonist on the back, for putting out the fire?
Andrew Sullivan assigns him to the "Dept. of Cojones".
We may have to assign him to our IDOTW.
I suppose, to be fair, Thain needs the heavy-duty cash, so he can fly, in his private corporate jet, to the next AIG Spa Getaway
Tuesday, November 25, 2008
Top Ten Cloves: Things About Citigroup Keeping Stadium Sponsorship After Getting Government Bailout
News Item: Heckuva Bailout: Citi and AIG Still Pay Hundreds Of Millions In Sports Sponsorship
10. Instead of 'Fan Appreciation Day', now will be called 'Hank Paulson Appreciation Day'
9. Make fans give back foul balls hit in stands, because Citigroup needs to "tighten belt and save money"
8. When starting pitcher is relieved, now will be referred to as being "bailed out"
7. Soon comes evident ... Free Agent Signing Season on one hand ... Major layoffs at Citigroup on the other hand
6. Citigroup making one concession - Killing plans that would allow execs to fly to stadium in their private jets
5. "Casey at the Bat" now gets reworked to "Casey at the Bank" and it's a happy ending - Casey doesn't strike out, but walks away with billions
4. Citigroup to sub-contract parking lot to AIG... AIG hires people to vandalize cars ... AIG then sells fans new "Vandalism Insurance Policy"
3. Instead of ceremonial "first pitch", Citigroup execs will do ceremonial reenactment of receiving bailout check from Government
2. New 7th Inning stretch tradition - Players and Citigroup shakedown fans in stadium, making them fork over money to see the game finished ...
1. Using their "expertise", Citigroup to make millions ... Working on packaging troubled batting averages and selling them to investors
Bonus Bogus Bailout Riffs
Think Progress: Bailed-out companies AIG, Citibank have no plans to cancel expensive sports sponsorships
Michael Winter: Citi, AIG will continue sports sponsorships despite bailouts
Robert Reich: Citigroup Scores
Tyler Cowen: Whoops! Back to TARP after all...
Brilliant at Breakfast: So why DID we just throw a truckload of money at Citigroup then?
The Wonk Room: Citigroup Bailout: ‘A Lousy Deal For The Taxpayers’
Mark Thoma: The Citigroup Bailout
Bonus Bonus
Special Essay - Play Ball! ... Batter Up! ... Could You Please Tell Me, What Is This Thing Called Baseball?